Here’s a paradox worth sitting with. The average FICO Score in the U.S. is 714, which is squarely in “good” territory. Yet the picture underneath the average is a split one. FICO’s spring 2026 report found that a record 48.1% of consumers now score 750 or higher, while lower-scoring borrowers face continued pressure.
So two people can live in the same city, earn similar incomes, and get very different answers from a lender. Understanding how credit scores work in the United States is what explains the gap, and it’s more learnable than most people think.
A credit score isn’t a mystery number handed down from above. It’s a summary of a handful of behaviors, calculated from data in your credit reports. This guide breaks down what goes into it, what doesn’t, and what you can actually do to move it.
[AUTHOR EXPERIENCE: If true, add 2–3 sentences about a real moment when your own credit score surprised you, and what you learned. Otherwise delete this line.]
What Is a Credit Score?
A credit score is a three-digit number that estimates how likely you are to repay borrowed money on time. Lenders use it to decide whether to approve you, and what interest rate to offer.
That’s the one-sentence version. The useful version is this: a score is a snapshot, not a verdict. It’s calculated from the data in your credit reports at a particular moment, and it changes as that data changes.
Credit score vs. credit report
People mix these up constantly, so let’s separate them.
- Your credit report is the raw record: your accounts, balances, payment history, inquiries, and any collections or bankruptcies.
- Your credit score is a calculation based on that report.
You get your reports from the credit bureaus. Scores come from scoring companies that run their formulas on your report data. A free report from the official site doesn’t necessarily include a score. Experian’s page on this notes that reports from AnnualCreditReport.com don’t include credit scores.
The three credit bureaus
In the U.S., three nationwide credit bureaus collect and maintain your data: Equifax, Experian, and TransUnion. Lenders choose which bureaus to report to, so your three files may not match exactly. One lender might report to all three, another to only one.
That’s the first reason your score looks different depending on where you check it. The score is calculated from a different file, and often by a different formula.
[Internal Link: “credit report vs. credit score: what’s the difference?”]
Score ranges
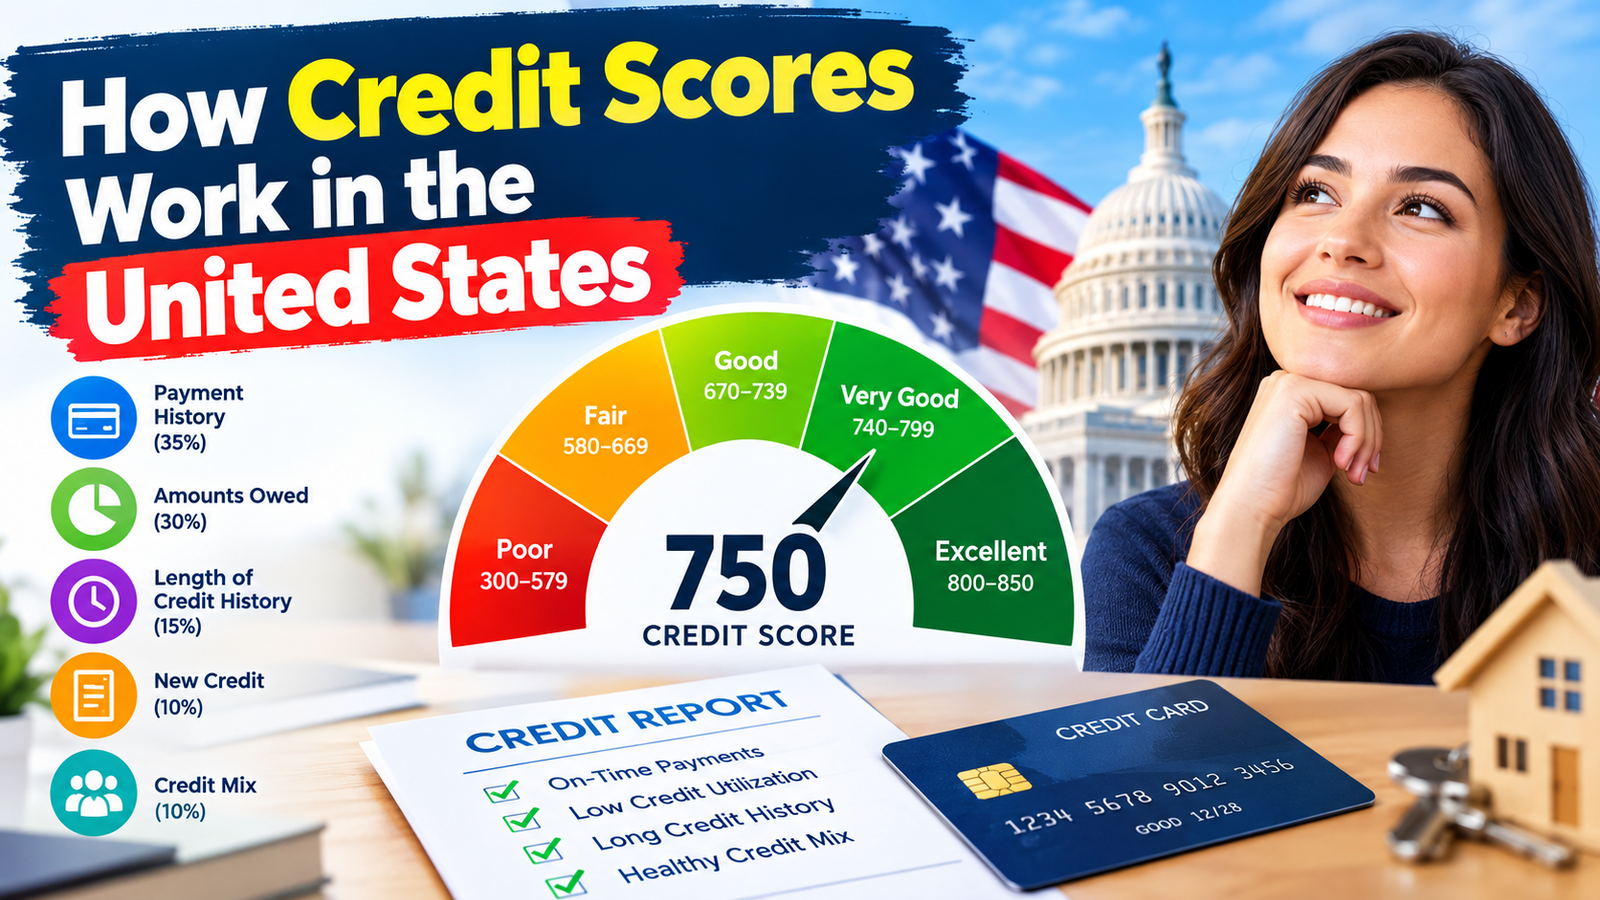
The most widely used scores, FICO and VantageScore, both run from 300 to 850. For FICO Scores, the commonly used bands are:
| Range | Label |
|---|---|
| 800–850 | Exceptional |
| 740–799 | Very good |
| 670–739 | Good |
| 580–669 | Fair |
| 300–579 | Poor |
Lenders set their own cutoffs, so these labels are guideposts, not guarantees. FICO says its scores are used by 90% of top U.S. lenders, which is why so much credit-score advice is written around FICO’s model. [VERIFY: confirm the range labels against FICO’s current published bands before publishing.]
Why this matters right now
The national picture has shifted recently. FICO reported that the average U.S. score slipped from 2025 into 2026, driven largely by resumed student loan delinquency reporting and a modest rise in mortgage delinquencies. Its more recent fall 2026 report found the average holding at 714, flat since October 2025 and down one point from a year earlier.
If you have federal student loans, or you’ve been coasting on autopilot for a few years, it’s a good time to check what your reports actually say.
Why Your Credit Score Matters: The Real Stakes
Most people think of a credit score as something you need for a mortgage. It touches more than that.
Who looks at your credit
- Lenders (mortgages, auto loans, credit cards, personal loans) use your score to decide approval and pricing.
- Landlords often check credit as part of a rental application.
- Insurers in many states use credit-based information when pricing certain policies. [VERIFY: rules vary by state.]
- Utility and phone providers may check credit to decide on deposits.
- Employers may, with your permission, review a credit report for some roles. They generally don’t see your score itself. [VERIFY: check FCRA rules before publishing.]
What a “good” score buys you
A higher score generally means more approvals and lower interest rates. Over the life of a car loan or mortgage, even a small rate difference can add up to real money. I’d rather not put a made-up dollar figure on it here, since it depends entirely on the loan, the term, and the market. The direction is what matters: better credit lowers the cost of borrowing.
The national picture
Two data points from FICO’s 2026 reports frame where Americans stand:
- The national average FICO Score is 714.
- The share of consumers scoring 750 or higher has climbed to a record 48.1%, up from 43.3% in 2019, while the share scoring below 550 grew slightly.
FICO’s own commentary describes this as a “K-shaped” pattern, where strong profiles are getting stronger while others fall behind. In plain terms, credit habits compound. Good habits tend to build on each other, and so do the bad ones.
[Internal Link: “how to check your credit report for free”]
How Credit Scores Work: The Five Factors, Step by Step
Here’s where most guides get vague. So let’s be specific.
FICO Scores are built from five categories. According to myFICO, they’re weighted as follows: payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%), and credit mix (10%). Those percentages reflect the general population, and the importance of each category can vary from person to person.
VantageScore uses different weightings and terminology, but the underlying behaviors are similar. Experian notes that the habits behind good FICO Scores tend to help on any score derived from credit report data.
Let’s go through each one.
Factor 1: Payment history (35%)
This is the heavyweight. Do you pay your accounts on time?
Myfico’s explanation is that your payment record is the strongest predictor of whether you’ll repay future debts as agreed, which is why it carries the most weight. Late payments are generally reported once they’re 30 days past due, and the severity increases at 60, 90, and 120-plus days.
One late payment isn’t necessarily a “score-killer” on a strong file, but the impact depends on your starting profile. Myfico’s research found the effect of a given credit action varies a lot depending on where you begin.
What to do: Set up autopay for at least the minimum on every account. Then pay the full statement balance when you can.
Factor 2: Amounts owed (30%)
This category looks at how much of your available credit you’re using, especially on revolving accounts like credit cards. That’s your credit utilization ratio.
To calculate it, divide a card’s balance by its limit. Scoring models look at the utilization on each card individually and across all your cards combined.
You’ve probably heard the “keep it under 30%” rule. Experian’s guidance uses 30% as a target to aim for. But FICO itself says there’s no single percentage that earns optimal points. Generally, lower utilization is associated with lower risk. Think of 30% as a rough checkpoint, not a finish line.
What to do: Keep balances low relative to limits, and pay down cards before the statement closes (more on that in the tips).
Factor 3: Length of credit history (15%)
This looks at how long you’ve had credit, including the age of your oldest account, your newest account, and the average across all of them.
In general, a longer history helps, all else being equal. And per FICO, payment history matters more than history length, so a short but spotless record can beat a long, messy one.
What to do: Don’t close your oldest accounts without a reason, especially cards with no annual fee. Keep them open and use them lightly.
Factor 4: New credit (10%)
Every time you apply for credit, the lender typically does a hard inquiry. FICO says one hard inquiry usually has a minimal effect on a score. Experian notes that inquiries stay on your reports for two years. Their effect on scores generally fades sooner. [VERIFY: check current FICO guidance on the 12-month scoring window.]
Checking your own score or report is a “soft” inquiry and doesn’t affect it.
What to do: Apply only for credit you actually need, and space out applications where you can.
Factor 5: Credit mix (10%)
Credit mix considers the variety of accounts you have: credit cards, retail accounts, installment loans, mortgages, and so on.
This is the least important lever, and I’d advise against gaming it. Experian and FICO both caution against opening accounts just to improve your mix. Mix tends to develop naturally as you go through life.
What to do: Nothing special. Don’t take on a loan you don’t need for a few points.
The Monthly Credit Rhythm
Here’s the routine I’d suggest turning all of this into. It takes about 15 minutes a month:
- Pay: Confirm autopay ran and every account is current.
- Trim: Look at card balances relative to limits. If any are high, pay them down before the statement date.
- Check: Glance at one of your reports (you can pull each bureau’s report weekly for free) for anything unfamiliar.
- Hold: Resist opening or closing accounts on impulse.
The FTC has confirmed that Equifax, Experian, and TransUnion have permanently extended their program allowing free weekly credit reports at AnnualCreditReport.com, and that’s the only site authorized to fill the free annual report orders required by law.
[Internal Link: “how credit utilization works and how to lower it”]
Common Credit Score Mistakes (and How to Avoid Them)
1. Believing you need to carry a balance. You don’t. You never have to pay interest to build credit. Paying your statement balance in full is the cheaper way to build a strong record. FICO’s own guidance notes that having balances doesn’t automatically mean you’re high-risk, but that’s different from saying you need to carry one.
2. Closing your oldest card. It can shrink your available credit and eventually shorten your credit history. If the card is free to keep, consider keeping it open.
3. Ignoring your reports. Errors happen, and each bureau keeps its own file, so a mistake can appear on one report and not the others. Reviewing your reports is how you catch it.
4. Paying a “credit repair” company to erase accurate items. The CFPB is direct on this: nobody has the right to remove accurate negative information from your report. You can only get errors fixed, and you can dispute them yourself for free.
5. Applying for several cards in a short stretch. Each application is a potential hard inquiry, and multiple new accounts can lower your average account age. Space them out.
6. Missing a payment because of a due-date mix-up. This is the most avoidable mistake of all. Autopay and calendar reminders exist for a reason.
7. Assuming one score is “the” score. You don’t have one credit score. You have many, from different models and different bureau files. Don’t panic over a 10-point gap between two apps.
8. Opening credit only to “build a mix.” As covered above, this is the weakest lever.
[AUTHOR EXPERIENCE: Add a real mistake you or someone you know made, if you have one to share.]
Expert Tips & Advanced Strategies
These go beyond the beginner advice.
1. Pay before the statement closes. Card issuers typically report your balance to the bureaus around your statement date, not your due date. If you pay down a balance before the statement closes, the reported balance can be lower, which can improve your utilization even if you pay in full anyway. [VERIFY: reporting timing varies by issuer.]
2. Use per-card utilization, not just the total. Because models consider utilization on individual cards as well as overall, one nearly maxed-out card can hurt even when your total looks fine. Spreading balances or paying down the highest-utilization card first can help.
3. Rate-shop within a window. When you’re shopping for an auto loan, mortgage, or student loan, scoring models generally treat multiple inquiries for the same loan type within a short window as a single inquiry. The window length depends on the scoring model. [VERIFY: current FICO rate-shopping windows.] Do your comparison shopping in a tight period.
4. Freeze your credit if you’re not applying for anything. A credit freeze restricts access to your file, which helps block new-account fraud. It’s free by law and doesn’t affect your score. You can lift it temporarily when you need to apply. [VERIFY: confirm current rules with each bureau.]
5. Dispute errors in writing and keep records. If you find a mistake, dispute it with the credit reporting company and the lender that supplied the data. Save confirmations. The CFPB accepts complaints if you can’t resolve an issue.
6. Know the clock on negative items. Most negative information can be reported for seven years, and Chapter 7 bankruptcies can stay up to ten. Positive accounts can stay on for at least 10 years. And a fresh negative hurts more than an old one. Myfico notes that the older a negative item is, the less it typically affects your score.
7. Check before a big application. If you’re planning to apply for a mortgage or car loan, pull your reports at least a few months ahead. That leaves time to fix errors and lower balances without rushing.
[Internal Link: “how to dispute an error on your credit report”]
A Worked Example, and Who This Is (and Isn’t) For
An illustrative example
The following is a hypothetical scenario to show the math. It isn’t a real person’s results, and actual score changes vary by individual. I’ve deliberately left out specific score numbers.
Imagine someone with two credit cards:
| Card | Limit | Balance | Utilization |
|---|---|---|---|
| Card A | $6,000 | $2,400 | 40% |
| Card B | $4,000 | $1,600 | 40% |
| Total | $10,000 | $4,000 | 40% |
They’ve never missed a payment, but both cards are running higher than the 30% checkpoint.
To get the combined ratio to 30%, total balances need to drop to $3,000. That’s a $1,000 paydown. Putting an extra $500 a month toward the cards would get there in two months. To reach 10%, balances would need to fall to $1,000 total.
What would change on the credit report? Nothing about payment history, since it was already clean. The main difference would be the amounts-owed category, which FICO weights at about 30%. That’s why utilization is often the fastest lever for people who already pay on time.
Note what didn’t change: no new accounts were opened, no old ones closed, and no inquiries were triggered.
Who should use these strategies
This approach fits you if you:
- Pay on time but feel your score is lower than it should be
- Are planning a major loan application in the coming months
- Are recovering from a rough patch and want a clear path
- Are new to credit and want to build good habits early
Who it may not fit
- If a mortgage or car loan application is only weeks away, avoid opening or closing accounts. Talk with your lender about your specific file.
- If you’re behind on payments or in debt trouble, score tactics are secondary to stabilizing your budget. Consider nonprofit credit counseling [VERIFY: link to reputable resources].
- If you’re tempted by credit repair services, be skeptical. As covered above, accurate negatives can’t be removed for a fee.
- If you’re thinking of borrowing just to “build credit,” slow down. You can build a record with a modest, manageable account you’d use anyway.
This is general educational information, not personalized financial advice.
Conclusion
Here’s what I’d want you to walk away with. Your credit score isn’t a mystery, and it isn’t a judgment of your character. It’s a summary of a few behaviors, mostly paying on time and not using too much of your available credit, calculated from data you can see for free.
Pay on time, keep balances low, keep good accounts open, apply for credit sparingly, and let time do the rest. Check your reports regularly so errors don’t linger. Remember that different scores and different bureaus will give different numbers, and that’s normal.
The people who end up with strong credit aren’t usually doing anything exotic. They’re doing a few simple things consistently.
Your next step: Go to AnnualCreditReport.com today and pull one of your three reports. Scan it for anything you don’t recognize. It takes ten minutes, it’s free, and it’s the single best starting point. And if this guide helped, leave a comment with the question you still have about your score.
4. Comparison Table: Common Credit Score Types
Which score a lender uses depends on the lender and the loan. This table covers the ones you’re most likely to run into.
| Feature | FICO Score 8 (widely used base model) | Newer FICO versions (9, 10, 10 T) | VantageScore 3.0 / 4.0 | Industry-specific FICO (auto, bankcard) |
|---|---|---|---|---|
| Typical range | 300–850 | 300–850 | 300–850 | 250–900 |
| Key characteristic | Long-standing general-purpose model | Adjust how collections are treated; 10 T uses trended data | Alternative model from the bureaus’ joint venture; different weightings | Tuned to predict risk for one loan type |
| Where you’ll see it | Many lenders and consumer tools | Some lenders; adoption varies | Free score apps and some lenders | Auto lenders and card issuers |
| Best for understanding | A solid general benchmark | Seeing how newer models may treat your file | What many free monitoring apps show | Preparing for an auto loan or card application |
| Difficulty to access | Moderate; often free via card issuers | Harder; less commonly offered to consumers | Easy; widely available free | Harder; often through paid FICO tools |
| Cost | Often free through issuers [VERIFY] | Varies [VERIFY] | Often free | Often paid [VERIFY] |
My take: Don’t obsess over which score is “real.” Track one consistently to watch the trend, and remember lenders may pull something different. Also [VERIFY] the current status of mortgage-scoring rules, since Fannie Mae and Freddie Mac’s accepted models have been changing.
5. FAQ Section
These follow the typical “People Also Ask” pattern for this topic. Confirm the exact questions in the live SERP before finalizing.
Q: What is a good credit score in the U.S.?
A: On FICO’s scale, scores from 670 to 739 are generally considered good, 740 to 799 very good, and 800 and up exceptional. For context, FICO reports the national average is 714. But “good” depends on the lender and the loan, since each sets its own cutoffs. In my view, it’s more useful to think in terms of trend and thresholds than a single number. If you’re comfortably in the 700s and paying on time, you’re in solid shape for most everyday borrowing.
Q: How is a credit score calculated?
A: A credit score is calculated from the information in your credit reports. For FICO Scores, the weights are roughly payment history at 35%, amounts owed at 30%, length of credit history at 15%, new credit at 10%, and credit mix at 10%. Those percentages describe the general population and can vary by person. Other models, like VantageScore, use somewhat different approaches. The exact formulas are proprietary, but the takeaway is simple: pay on time and keep balances low relative to your limits.
Q: What are the five factors that affect your credit score?
A: The five FICO categories are payment history, amounts owed (including credit utilization), length of credit history, new credit, and credit mix. Payment history and amounts owed together make up about 65% of the score, so they deserve most of your attention. Honestly, I think people spend far too much energy on credit mix and far too little on autopay. If you only fix two things, make them on-time payments and lower card balances.
Q: Does checking my credit score lower it?
A: No. Checking your own score or report is a soft inquiry and doesn’t affect your score. Hard inquiries happen when you apply for credit and a lender reviews your file. FICO says a single hard inquiry usually has a minimal effect. Hard inquiries remain on reports for two years, though their scoring impact generally fades sooner. So check as often as you like. Regular monitoring is one of the best ways to catch errors or fraud early.
Q: How can I check my credit score for free?
A: Many card issuers, banks, and lenders offer free scores to customers, and various consumer services do too. Keep in mind that reports and scores are different things. You can get free credit reports from all three bureaus weekly at AnnualCreditReport.com, but those reports don’t include scores. Also, free scores may use a different model than your lender does, so don’t be alarmed by differences. Stick to official or reputable sources, and be cautious of sites asking for payment details.
Q: Why is my credit score different on different websites?
A: Because there isn’t just one credit score. Different sites may use different scoring models (FICO or VantageScore, and different versions of each) and pull data from different bureaus. Your three credit files can also contain slightly different information, since lenders don’t always report to all three. And scores update when new data arrives, so timing matters too. In my experience, a gap of a few points is nothing to worry about. Focus on the direction of change instead.
Q: How long do late payments stay on my credit report?
A: Under federal law, most negative information, including late payments, can generally be reported for seven years. Chapter 7 bankruptcies can be reported for up to ten. The seven-year clock generally runs from the first missed payment that led to the entry. The good news is that impact fades with time, and recent behavior counts more than old mistakes. If you’ve slipped, the best response is getting current and staying current. Meanwhile, check that the dates on your report are accurate.
Q: What’s the difference between FICO and VantageScore?
A: Both estimate credit risk on a 300 to 850 scale using data from your credit reports, but they’re different formulas from different companies. FICO scores have long been the standard in lending, and FICO says its scores are used by 90% of top U.S. lenders. VantageScore is widely offered in free monitoring apps. They weigh factors somewhat differently, so the numbers can differ. My advice is to follow one consistently and not fret over small gaps between them.
Q: How long does it take to build credit from scratch?
A: There’s no exact timeline, but FICO generally needs at least one account that has been open for a while and recently reported before it can calculate a score. [VERIFY: check FICO’s current minimum requirements.] From there, steady on-time payments and low balances build a record over months and years. A longer history helps, but FICO says payment history matters more than history length. So start small, pay on time, and be patient. Don’t rush into borrowing you don’t need.
Q: How fast can I raise my credit score?
A: It depends on what’s holding it down. If high card balances are the issue, paying them down can help relatively quickly, since utilization reflects current balances. Late payments and collections take longer, because their impact fades gradually as they age and you add positive history. Be wary of anyone promising overnight results. Honestly, the most reliable fixes are boring ones: pay on time, lower balances, and fix genuine errors. Results vary by individual, and this isn’t personalized advice.