According to the Federal Reserve, the average American household has a net worth of about $1.06 million. The median household? $192,900. Same country, same survey, and the two numbers sit more than five times apart.
That gap is why so many net worth comparisons online are misleading, and why so many people feel behind for no good reason. If you’ve wondered what net worth actually is, how to calculate it, and what a “normal” number looks like, you need three things: the right definition, the right math, and the right benchmark.
Here’s what you’ll get in this guide: your own number (or exactly how to find it in about 30 minutes), an explanation of what it’s telling you, and a clear sense of which comparisons are worth making. We’ll cover the formula, a worked example, the mistakes that trip people up most, and a simple tracking system that doesn’t require special software.
What Is Net Worth? The Real Definition
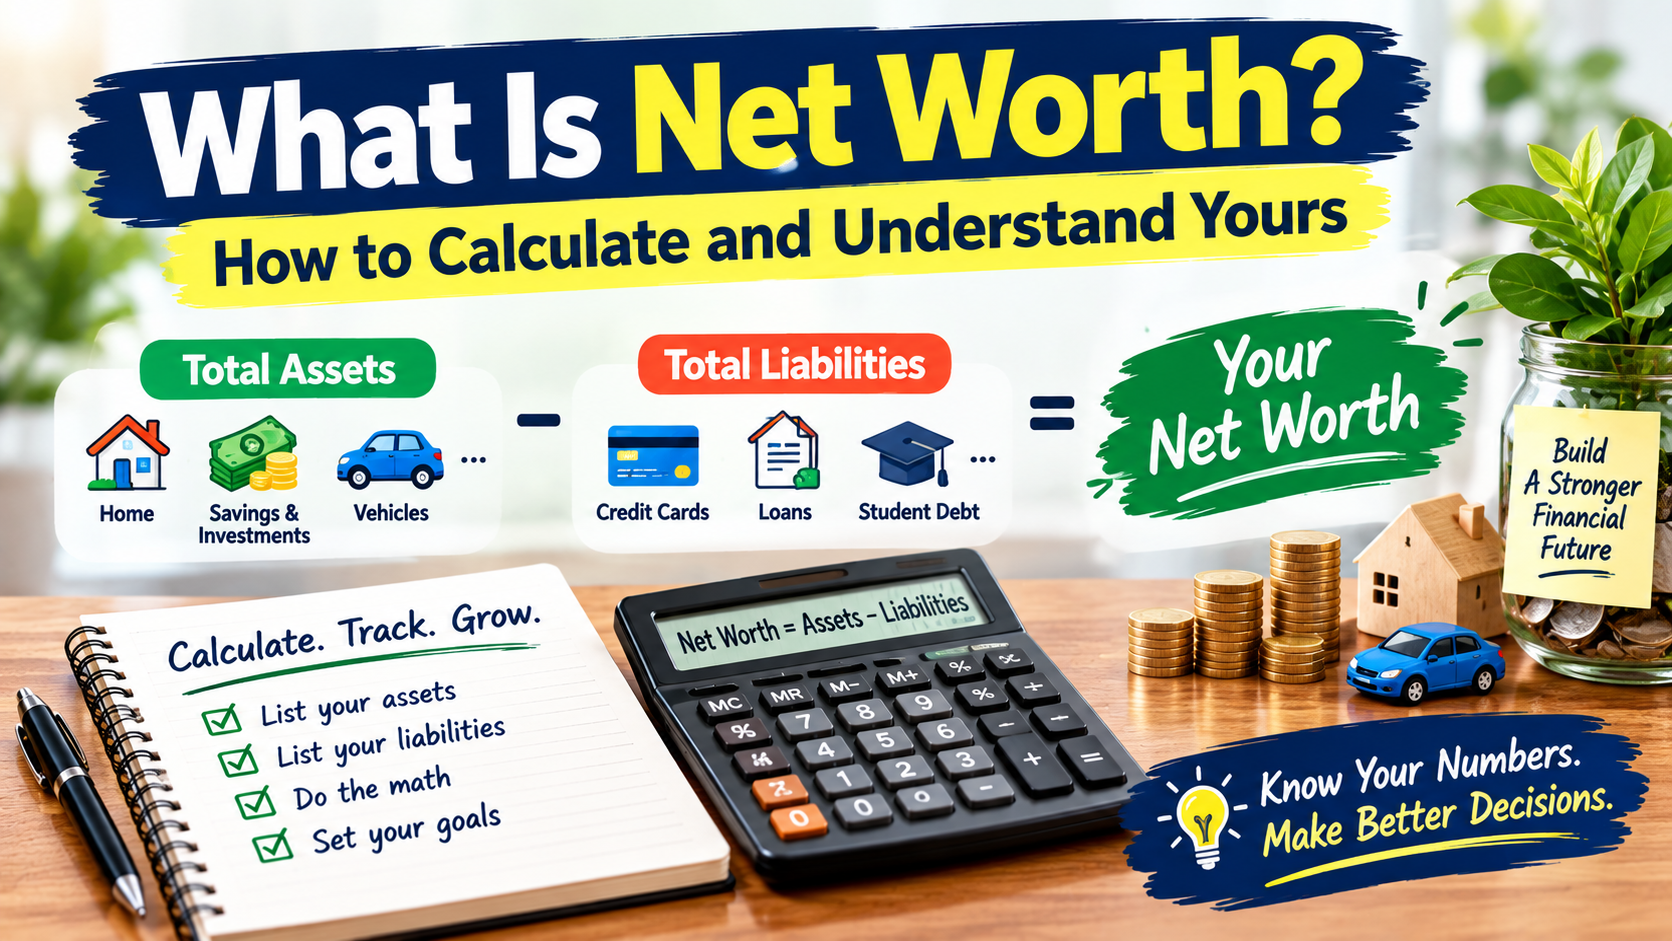
Net worth is the total value of everything you own (your assets) minus everything you owe (your liabilities). It’s a snapshot of your financial position on one specific day.
Net worth = Assets − Liabilities
If you own more than you owe, your net worth is positive. If you owe more than you own, it’s negative. That’s common early in adult life, especially with student loans, and it’s not a verdict on your character.
Two details people miss:
- It’s a snapshot, not a movie. Your number changes with markets, home values, and debt balances, sometimes daily.
- It’s measured at current market value, not what you paid. Your house is worth what a buyer would pay, not your purchase price.
What counts as assets
An asset is anything you own that has monetary value. The main categories:
- Cash and savings: checking, savings, money market accounts, CDs
- Investments: brokerage accounts, stocks, bonds, funds, crypto you hold
- Retirement accounts: 401(k), IRA, Roth IRA, pensions with a balance
- Real estate: your home and any other property, at estimated market value
- Vehicles: at current resale value, not what you paid
- Business ownership: your stake, valued conservatively
- Valuables: jewelry, art, collectibles, at what they’d realistically sell for
My simple test: If I had to sell or cash this out today, roughly what would I get? That’s the number to use.
What counts as liabilities
A liability is any debt or financial obligation. Include everything:
- Mortgage and home equity lines of credit (HELOCs)
- Auto loans
- Student loans
- Credit card balances
- Personal loans and buy-now-pay-later balances
- Medical debt
- Taxes you owe
- Loans against your 401(k), and money borrowed from family
For context on how common these are, the Fed’s survey found the most frequently reported liabilities were credit card debt (45% of households), residential mortgages (42%), and vehicle loans (35%). And the New York Fed reports total U.S. household debt reached $18.8 trillion in Q2 2026. Debt is a mainstream part of household balance sheets. It’s the mix and the cost that matter.
Net worth vs. income vs. cash flow
These three get confused constantly, so let’s separate them.
- Income is what you earn.
- Cash flow is what’s left after spending each month.
- Net worth is what you’ve kept and built over time.
You can have a high income and a low net worth (earn $200,000, spend $200,000), or a modest income and a growing net worth. Honestly, I’d rather have a $70,000 earner whose net worth climbs every year than a $200,000 earner whose number stays flat. Net worth measures what your income has actually done.
Useful variations of net worth
Your total number doesn’t tell the whole story, so pros often look at variations:
- Net worth excluding home equity: total net worth minus the value of your primary residence (net of the mortgage). It shows what you have outside your house.
- Investable assets: cash, brokerage, and retirement accounts. Money that can work for you or fund your future.
- Liquid net worth: cash and things you can convert to cash quickly, minus short-term debts.
For a real-world example of why the “excluding home” idea matters, the SEC’s accredited-investor rules exclude your primary residence when testing the $1 million net worth threshold.
Why this matters right now in 2026
The best benchmark we have is still the Fed’s 2022 Survey of Consumer Finances, and the 2025 edition is expected to be published in late 2026. That 2022 survey caught a historic moment: median net worth jumped 37% between 2019 and 2022, the largest three-year increase in the modern survey’s history, according to the Fed’s report. Since then, inflation, interest rates, and home prices have all shifted, so treat the benchmarks below as a starting point, not a verdict.
Why Net Worth Matters: The Real Stakes
The scoreboard that doesn’t lie
Here’s my honest view: net worth is the most honest single number in personal finance. Income can be flashy. Spending can be hidden. Credit scores measure borrowing behavior. But net worth reflects everything at once: your savings habits, your debt costs, your investments, your home’s value, and what you’ve done with your earnings over the years.
It also tells you about resilience (can you absorb a shock?), options (can you change careers or take a break?), and direction (are you moving forward or standing still?). The direction matters more than the level.
[AUTHOR: Add a brief, honest moment about the first time you calculated your own net worth: what surprised you.]
What the data says by age
The Fed’s 2022 survey found median household net worth ranging from about $39,000 for households under 35 to about $410,000 for ages 65–74. Here’s the breakdown:
| Age group | Median net worth (2022 SCF, approx.) |
|---|---|
| Under 35 | about $39,000 |
| 35–44 | about $135,000 |
| 45–54 | about $247,000 |
| 55–64 | about $364,000 |
| 65–74 | about $410,000 |
| 75+ | about $335,000 |
| All households | about $192,900 |
Notice the shape: net worth climbs through your working years, peaks in the mid-60s to mid-70s, then declines as people spend down assets in retirement.
Mean vs. median: the comparison trap
The overall mean (average) net worth was about $1,063,700, while the median was $192,900. The average gets pulled far upward by a small number of very wealthy households. The median is the number in the middle: half of households have more, half have less.
For benchmarking yourself, use the median. One analysis of the same survey data puts the 90th percentile at roughly $1.94 million, which shows just how far the top of the distribution stretches from where most people sit.
And remember what these numbers include. Household net worth counts home equity, retirement accounts, and business ownership, and it includes inheritances. A median-aged household’s net worth isn’t a savings account balance. It’s mostly a house and a retirement account.
How to Calculate Your Net Worth: The Four-Number Snapshot
Most guides stop at “assets minus liabilities.” That’s step one. I use what I call the Four-Number Snapshot, because one number hides too much:
- Net worth (assets − liabilities)
- Net worth excluding home equity
- Investable assets
- Debt-to-asset ratio (liabilities ÷ assets)
Here’s how to build it in about 30 minutes.
Step 1: Gather your information
Pull up bank and brokerage statements, retirement account balances, loan statements, and credit card balances. Your credit report can help you catch forgotten debts. [Internal Link: “credit report vs. credit score: what’s the difference?”]
You don’t need special software. A notebook or a simple spreadsheet works fine.
Step 2: Value your assets conservatively
Accuracy beats optimism. Some rules I follow:
- Cash and investments: use today’s balance.
- Home: use recent comparable sales, not your hoped-for price. For a conservative view, consider subtracting typical selling costs.
- Vehicles: use current private-party or trade-in value, not what you paid.
- Retirement accounts: use the current balance. (More on taxes in the tips section.)
- Valuables: use realistic resale prices, not insured or replacement value.
- Business ownership: be conservative; an illiquid stake isn’t worth what you hope it is.
Step 3: List every liability
Write down every balance you owe, including the ones that are easy to forget: buy-now-pay-later plans, a 401(k) loan, medical bills, or money owed to family.
Step 4: Do the math
Add up assets. Add up liabilities. Subtract.
Step 5: A worked example
Here’s a hypothetical mid-career household:
| Assets | Value |
|---|---|
| Cash accounts (checking, savings) | $18,000 |
| 401(k) | $72,000 |
| Roth IRA | $21,000 |
| Brokerage account | $9,000 |
| Home (estimated market value) | $340,000 |
| Vehicle | $16,000 |
| Total assets | $476,000 |
| Liabilities | Balance |
|---|---|
| Mortgage | $262,000 |
| Auto loan | $11,500 |
| Student loans | $18,000 |
| Credit card | $3,500 |
| Total liabilities | $295,000 |
Net worth: $476,000 − $295,000 = $181,000.
Now the Four-Number Snapshot:
| Metric | Result | What it tells you |
|---|---|---|
| Net worth | $181,000 | Overall position |
| Net worth excluding home equity | $103,000 | What they’d have outside the house |
| Investable assets | $120,000 | Cash, retirement, and brokerage combined |
| Debt-to-asset ratio | 62% | Liabilities are 62% of assets |
The most interesting insight isn’t the headline number. Home equity ($340,000 − $262,000 = $78,000) is about 43% of their net worth. They’re “house-rich”: a big chunk of their wealth is tied up in a home they live in. That doesn’t mean it’s wrong, but it shapes decisions about liquidity, retirement readiness, and where new dollars should go.
Step 6: When your number is negative
Here’s a hypothetical early-career example:
- Assets: $6,000 cash + $3,000 in a 401(k) + a $9,000 car = $18,000
- Liabilities: $32,000 student loans + $7,000 car loan + $1,200 credit card = $40,200
- Net worth: −$22,200
That’s not a failure. It’s a starting point, and a very common one. The goal is direction: a negative number that’s rising is a good sign, and we’ll see how that plays out in the scenarios below.
Step 7: Set a tracking rhythm
Recalculate monthly or quarterly, on the same date each time, and log the results in a simple table. Daily checking just measures market noise. What you want is a trend line.
[Internal Link: “how to build a monthly budget from scratch”]
Common Mistakes People Make (and How to Avoid Them)
Honestly, most people get net worth wrong in a handful of predictable ways.
1. Overvaluing assets.
Using the purchase price of a car, an optimistic home estimate, or the insured value of jewelry inflates your number and gives false comfort. Use what you could realistically sell it for.
2. Forgetting liabilities.
Buy-now-pay-later balances, medical bills, taxes owed, and 401(k) loans often get left out. A complete inventory matters more than a flattering one.
3. Comparing yourself to averages.
The mean is skewed by the ultra-wealthy, and comparing to social media is worse. Use the median for your age group, and treat it as directional.
4. Treating home equity like spending money.
A house is an asset, but you can’t spend your living room. Look at net worth excluding home equity and investable assets to see the full picture.
5. Checking it constantly.
Your number moves with the markets every day. Obsessing over daily changes leads to bad decisions. Monthly or quarterly is enough.
6. Treating a negative or low number as a failure.
It’s a starting line. What matters is what you do next and how the number moves over the next 12–24 months.
7. Ignoring what’s behind the number.
Two people with the same net worth can be in very different places: one with $50,000 in cash and $50,000 of debt, another with $0 in each. Look at composition, not just the total.
[AUTHOR: If you’ve made one of these mistakes yourself, say which and what changed once you noticed. Readers trust the honest version.]
Expert Tips & Advanced Strategies
If you’ve read a few beginner explainers, this is the material they skip.
1. Track why your net worth changed.
When your number moves, break the change into four buckets: savings (money you added), debt paydown, market movement, and asset appreciation or depreciation. It tells you which parts you control. Savings and debt paydown are yours; market moves aren’t. This one habit keeps you from taking credit (or blame) for things you didn’t do.
2. Build a “conservative” version alongside the headline.
Traditional 401(k) and IRA balances are pre-tax; you’ll owe taxes when you withdraw. Some planners mentally haircut them (for example by 20–25%) to get a more realistic spending-power view. In our example, that would lower the number by roughly $15,000–$18,000. Add a selling-cost haircut on your home if you’d like an even harsher view. If the conservative number still looks healthy, you’re on solid ground.
3. Remember that paying off debt is a return.
Paying off a credit card at the current average rate of 19.56% is the equivalent of a guaranteed 19.56% return on that money, which is hard to match anywhere else. It’s one reason many people tackle high-rate debt before extra investing. [Internal Link: “how to build a debt repayment plan you can stick with”]
4. Don’t confuse net worth with liquidity.
A high net worth locked in a house and retirement accounts won’t help if your car dies and you have no cash. Pair your net worth tracking with an emergency fund. [Internal Link: “emergency fund explained: how much should you save?”]
5. Use net worth excluding home for retirement thinking.
If you plan to keep living in your home through retirement, home equity won’t fund your groceries. Investable assets are the better indicator of retirement readiness.
6. Treat rules of thumb as curiosities, not standards.
One well-known heuristic from The Millionaire Next Door (1996) estimates “expected” net worth as age × pre-tax income ÷ 10. For a 40-year-old earning $80,000, that’s $320,000. It’s a fun reference, but it’s dated and ignores inheritance, region, and family situation. Similarly, salary-multiple guidelines you’ll see for retirement savings apply to retirement accounts, not total net worth.
7. Recalculate after life events.
Marriage, a child, a job change, an inheritance, buying a home, or a divorce all shift your balance sheet. Update your snapshot right after big changes, not just on schedule.
Real Scenarios: What This Looks Like in Practice
These are composite scenarios built from common patterns, with rounded numbers. They aren’t real people or guaranteed outcomes.
Scenario 1: From negative to positive
Jordan, 27, starts at −$22,200 (the example above). Over 24 months, Jordan captures a 401(k) employer match, builds a small emergency fund, and pays down debt. Assets grow by about $12,500 (cash up $5,000, retirement up $9,500, offset by about $2,000 of car depreciation). Liabilities fall by about $11,700 (student loans down $7,000, car loan down $3,500, credit card cleared).
The result: net worth moves from −$22,200 to about +$2,000, a swing of roughly $24,200. Jordan’s income didn’t change dramatically. The direction did. Using the “why did it change” bucket method, most of the gain came from choices Jordan controlled.
Scenario 2: The “house-rich” household
The mid-career household from our worked example ($181,000 net worth) realizes that 43% of it is home equity. Net worth excluding home is $103,000, and investable assets are $120,000. Nothing is wrong, but they decide to raise their retirement contribution rate and keep a larger cash buffer, rather than sending every spare dollar to the mortgage.
The point isn’t that their choice is right for everyone. It’s that they could see the tradeoff because they calculated more than one number.
Scenario 3: The pre-retiree
A couple in their late 50s has a net worth of about $1.1 million, but roughly 60% of it is home equity, and much of the rest is in pre-tax retirement accounts. They calculate their conservative net worth and their investable assets, and start planning how a future spend-down would work, including whether downsizing makes sense. A high headline number told them little; the composition told them what to plan for.
[AUTHOR: If you have a real story with real numbers, swap it in here.]
Who should use this approach, and who shouldn’t
This is a great fit if:
- You’ve never calculated your net worth
- You’re making a big decision (buying a home, changing careers, starting a business)
- You want a clear way to measure progress beyond your paycheck
- You suspect you’re doing better, or worse, than you think
Adjust it, or get personal help, if:
- You’re in financial crisis. If you’re behind on bills, focus on cash flow and essentials first. A balance sheet won’t fix a monthly shortfall.
- You have complex assets. Business interests, equity compensation, trusts, or divorce settlements can make valuation tricky. A fee-only fiduciary planner or accountant can help.
- You check numbers compulsively. If tracking fuels anxiety, cut back to quarterly.
- You’re tempted by account-linking tools. Apps that connect to your accounts can be convenient, but read their privacy policies and understand what access you’re granting.
I’m not a licensed financial advisor, and nothing here is personalized advice.
Conclusion: Know Your Number, Then Move It
Here’s what I’d want you to walk away with. Net worth is simple to calculate and surprisingly easy to misunderstand. It’s assets minus liabilities, but the real value is in the details: which assets, which debts, and what direction you’re heading.
Use the Four-Number Snapshot: total net worth, net worth excluding home, investable assets, and debt-to-asset ratio. Value things conservatively, compare yourself to the median for your age (not the average), and track it on a schedule instead of obsessing daily.
Do one thing this week. Set a 30-minute timer, list your assets and liabilities, and do the subtraction. Write the date next to your number. In three months, do it again.
Then tell me in the comments: were you surprised by your number, or by its composition? I’d love to hear what you found.
4. Comparison Table: Ways to Track Your Net Worth
| Method | Setup effort | Accuracy control | Cost | Privacy | Best for | Watch out for |
|---|---|---|---|---|---|---|
| Spreadsheet (DIY) | Moderate (about an hour to build a template) | High: you control every number and category | Free | High (data stays with you) | People who like control and customization | Requires discipline to update manually |
| Pen and paper (quarterly snapshot) | Low | High for simple situations | Free | Highest | Beginners and low-tech preferences | Harder to see trends or chart progress |
| Net-worth tracking apps (linked accounts) | Low to moderate | Medium: automated, but manual assets need updating | Often free, some paid tiers | Lower: you’re granting account access to a third party | People who want automation and charts | Check privacy policies; auto-valuations of homes and cars can be off |
| Bank or brokerage dashboards | Very low | Low: usually shows only that institution’s accounts | Usually free | Medium | Quick checks on a single account | Incomplete picture; rarely includes debts elsewhere |
| Financial planner’s tools | Moderate (meeting and data gathering) | High, with professional review | Varies (advisor fees) | Depends on the firm | Complex situations: business, equity comp, estate planning | Fees and conflicts of interest; choose a fiduciary |
My take: Start with a spreadsheet or even pen and paper for your first two snapshots. It forces you to look at every number, which is the whole point. Move to an app later if you want automation, and keep a manual check on the numbers that matter.
[Internal Link: “best net worth tracking tools compared”]
5. FAQ Section
Q: What is net worth?
A: Net worth is the total value of everything you own (assets) minus everything you owe (liabilities). Assets include cash, investments, retirement accounts, real estate, and vehicles. Liabilities include mortgages, student loans, car loans, and credit card balances. The result is a snapshot of your financial position on a given day. A positive number means you own more than you owe; a negative number means the opposite, which is common early in adult life.
Q: How do you calculate net worth?
A: List every asset at its current market value, then list every debt you owe. Add up each side and subtract liabilities from assets. For example, $476,000 in assets minus $295,000 in liabilities equals $181,000 in net worth. I also recommend calculating net worth excluding your home, plus your investable assets, so you see the whole picture. Recalculate monthly or quarterly, on the same date each time, to track your trend.
Q: What is a good net worth for my age?
A: Use the median, not the average. The Federal Reserve’s 2022 survey found median household net worth of about $39,000 under 35, $135,000 for ages 35–44, $247,000 for 45–54, $364,000 for 55–64, and $410,000 for 65–74. Those are benchmarks, not rules. My view: your own trend matters more than any comparison, since your income, region, family situation, and inheritance all change what “good” means.
Q: Does net worth include your home?
A: Yes, in the standard calculation. Count your home at its estimated market value as an asset and your mortgage as a liability, so what counts is your equity. But many planners also track net worth excluding home equity, because you can’t easily spend the house you live in. In my opinion, the excluding-home number is often the more honest indicator of retirement readiness and financial flexibility.
Q: Can your net worth be negative?
A: Absolutely. If you owe more than you own, your net worth is negative. It’s especially common for recent graduates carrying student loans, or for people early in building assets. It isn’t a character judgment. What matters is the direction: a negative number that’s rising through debt paydown and savings is a healthy sign. Track it every few months and focus on the trend, not the starting point.
Q: What is the difference between net worth and income?
A: Income is what you earn over a period, like a year. Net worth is what you’ve accumulated and still own after subtracting debts. A person can earn a high income and have a low net worth if they spend most of what they make, while someone with modest income can build meaningful net worth over time. I think net worth is the better measure of whether your money is actually working for you.
Q: Should retirement accounts count toward net worth?
A: Yes, count the current balance of your 401(k), IRA, and similar accounts as assets. Just remember that traditional (pre-tax) accounts will be taxed when you withdraw, so their spending power is lower than the balance suggests. Some people mentally reduce those balances for a more conservative figure. Roth accounts hold after-tax money, so qualified withdrawals are generally tax-free, which makes them closer to face value.
Q: How often should I calculate my net worth?
A: Monthly or quarterly is plenty for most people. Daily or weekly checking mostly measures market noise and can trigger emotional decisions. Pick a consistent date, like the first of the month or the end of each quarter, and record the number in a simple log. My advice: also recalculate after major life events like a new job, a home purchase, an inheritance, or a marriage.
Q: What is the difference between average and median net worth?
A: The average (mean) adds up everyone’s net worth and divides by the number of households, so a few extremely wealthy households pull it way up. The median is the middle value, where half of households have more and half have less. In the Fed’s 2022 survey, the mean was about $1,063,700 and the median $192,900. For personal benchmarking, the median is the more realistic yardstick.
Q: How can I increase my net worth?
A: There are four levers: earn more, spend less than you earn, pay down expensive debt, and invest consistently for the long term. In practice, savings rate and debt costs are what you control; market returns aren’t. I’d start with a starter emergency fund, capture any employer retirement match, and tackle high-interest debt, since paying off a card near the average 19.56% rate is like a guaranteed return. Then automate saving and investing so it happens without willpower.